Does insurance cover massage therapy?
Sometimes. Health plans may cover massage therapy when it is medically necessary, prescribed, and provided by an eligible licensed therapist, but many plans exclude it entirely. Coverage is also possible through no-fault auto claims and workers’ compensation. Medicare does not cover massage therapy.
Key facts
- There is no universal rule — coverage is set by your specific plan document, not by your insurer’s logo.
- Medical necessity and a documented diagnosis are the usual threshold; relaxation massage is not covered.
- Medicare does not cover massage therapy.
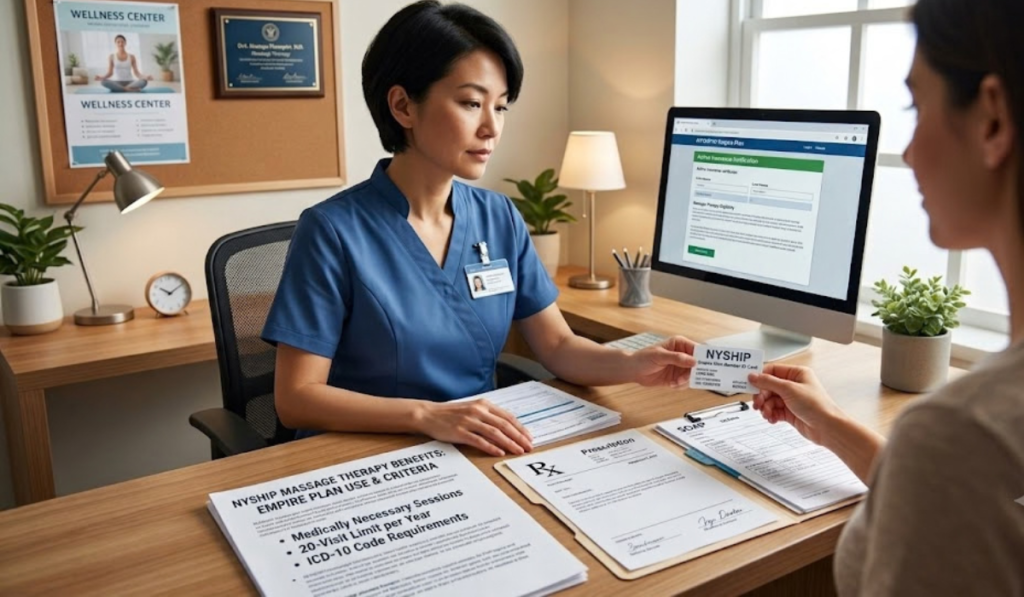
- The Empire Plan under NYSHIP covers up to 20 medical massage visits per calendar year, subject to deductible and coinsurance.
- New York is a no-fault auto state, so treatment after a car accident may run through the auto claim rather than health insurance.
- Workers’ compensation may cover treatment for a work-related injury.
- HSA and FSA funds can often be used with a letter of medical necessity.
- Circle Wellness MD bills NYSHIP directly; patients with other plans are self-pay.
Most people asking this question have already been told two contradictory things: that insurance never covers massage, and that their colleague gets it covered every month. Both can be true, because they are describing different routes to payment.
There are five of them, and they have very different odds. Working out which one applies to you takes one phone call and about ten minutes.
The five ways massage gets paid for
A health plan medical benefit
Some plans cover massage therapy as a medical service when it treats a diagnosed condition. Many exclude it outright, and some cover manual therapy only when a physical therapist, chiropractor or physician performs it rather than a licensed massage therapist.
The strongest local example is the Empire Plan under NYSHIP, which covers up to 20 medical massage visits per calendar year subject to the annual deductible and 20 percent coinsurance. If you are a New York State or participating-agency employee, this is probably your route, and our NYSHIP guide covers the rules in detail.
A no-fault auto claim
New York is a no-fault state, which means medical treatment after a motor vehicle accident is generally handled through the auto policy rather than your health plan. Prescribed treatment for injuries sustained in the accident may be covered under that claim.
Practical points: report the accident and open the claim promptly, get the treatment prescribed and linked to the accident in your provider’s notes, and check with the no-fault carrier what it will authorise before starting a course of care. Rules and deadlines are strict, and the carrier decides.
Workers' compensation
If the injury happened at work, treatment may be covered through the workers’ compensation claim. As with no-fault, it runs on its own rules, authorisations and provider requirements rather than on your health plan’s.
Start with the claim, not with the booking. Ask the claim manager what is authorised before arranging treatment.
HSA or FSA funds
Health savings and flexible spending accounts can frequently be used for massage when it treats a medical condition rather than providing general relaxation. Most administrators want a letter of medical necessity from your provider, plus an itemised receipt.
This is the route people most often miss. It does not make treatment free, but it means paying with pre-tax money, and it works even when your health plan excludes massage entirely. Your account administrator makes the final call.
Self-pay
Most massage in the United States is paid for directly. That is not a failure of planning — for relaxation or general wellness, no route to coverage exists in the first place, because plans pay for treatment of conditions.
If you are self-paying, ask for an itemised receipt anyway. It costs nothing and it is what an HSA or FSA claim runs on later.
Why so many plans say no
The two that decide individual claims are narrower. First, medical necessity: plans pay to treat a diagnosed problem, and for massage the bar usually involves both pain and some loss of function, documented. Second, provider eligibility: a therapist licensed by New York State is legally able to practise, but that does not oblige an insurer to recognise them as a billable provider. Plenty of denials come down to that distinction rather than to the treatment itself.
The five ways massage gets paid for
- Is massage therapy a covered service, or an exclusion? If it is excluded, nothing else matters — a prescription cannot override a plan exclusion.
- Can a licensed massage therapist bill independently? Some plans cover the technique only when a PT, chiropractor or physician performs it.
- In-network, out-of-network, or neither? Out-of-network usually means a separate deductible, lower reimbursement and possible balance billing.
- What documentation is required? Prescription, diagnosis code, prior authorisation, treatment notes, filing deadline.
Four yeses and you have a realistic claim. One no in the first question and you have your answer immediately, which is worth knowing before you book rather than after.
How to check your benefits in one call
Call the number on the back of your card and ask
- Does my plan cover massage therapy, or is it excluded?
- Can a New York licensed massage therapist bill my plan directly?
- Do I have out-of-network benefits for it?
- Do I need a prescription, referral or prior authorisation?
- Is there an annual visit limit, and is it shared with physical therapy or chiropractic?
- What is my deductible, and how much of it has been met this year?
- What is my copay or coinsurance for this service?
- Can I submit my own claim, and what is the filing deadline?
If you have NYSHIP or the Empire Plan
The clearest path of any plan we see
The Empire Plan covers massage therapy under its Basic Medical Program, up to 20 visits per calendar year, subject to the annual deductible and 20 percent coinsurance. Acupuncture works differently and, with a participating provider, carries no annual visit limit.
Circle Wellness bills NYSHIP directly. Our full NYSHIP guide covers what your referring provider needs to document, how the visit limits work, and what to ask when you call the Plan.
If you have Blue Cross Blue Shield
No single national answer
BCBS is a group of independent companies administering many different employer, individual, federal and self-funded plans. Two people holding BCBS cards can have entirely different massage benefits, and with a self-funded employer plan it is the employer’s plan document that governs rather than the insurer’s standard policy. Our BCBS coverage guide walks through how to check yours.
Medicare, Medicaid and massage
Medicare does not cover massage therapy. Some Medicare Advantage plans include supplemental wellness or complementary-care benefits, and those vary by plan and by year — ask whether massage itself is included, which providers qualify, and what the annual limit is. Medicaid coverage of massage is limited and varies by state.
Myth vs fact
| What people believe | What is actually true |
|---|---|
| Insurance never covers massage | Some plans do, and no-fault auto claims, workers’ compensation and NYSHIP are all real routes. The blanket “never” costs people benefits they already have. |
| A prescription guarantees coverage | A prescription supports a claim. It cannot override a plan exclusion, and it does not make an ineligible provider eligible. |
| Covered means free | Deductibles, coinsurance, visit limits and out-of-network allowed amounts all still apply. |
| My friend has the same insurer, so I have the same benefits | Employer plans, self-funded plans and individual plans differ under the same brand. Your plan document governs, not the logo. |
| Benefit verification means the claim will be paid | Every insurer states that verification is not a guarantee of payment. Record the call reference anyway. |
| If my plan excludes massage, I have no options | HSA and FSA funds can often be used with a letter of medical necessity, and that route works independently of whether your plan covers the service. |
Medicare, Medicaid and massage
We bill NYSHIP directly. Patients with other insurance are self-pay, and we will provide itemised documentation you can submit to your plan, your HSA or FSA administrator, or a no-fault or workers’ compensation claim.
What we will not do is tell you your treatment will be reimbursed. We do not hold your benefit information and we do not make coverage decisions — your plan does. What we can do is make sure the paperwork on our side is not the reason a claim fails.
FAQs
Does health insurance cover massage therapy?
Some plans do when the care is medically necessary, documented and provided by an eligible therapist. Many exclude it. Your plan document decides, so call the number on your card and ask whether massage therapy is covered or excluded.
Does Medicare cover massage therapy?
No. Some Medicare Advantage plans offer supplemental wellness benefits that may include it, varying by plan and year.
Can I use my HSA or FSA for massage?
Often, when the massage treats a medical condition rather than providing relaxation. Most administrators want a letter of medical necessity and an itemised receipt. The administrator makes the final decision.
Is massage covered after a car accident in New York?
Possibly, through the no-fault auto claim rather than your health plan. Open the claim promptly, have the treatment prescribed and linked to the accident, and confirm what the carrier will authorise before starting care.
Does workers' compensation cover massage?
It may, for a work-related injury, under that claim’s own authorisation rules. Ask the claim manager before arranging treatment.
Why was my massage claim denied?
Common reasons are a plan exclusion, an ineligible provider, missing authorisation, medical necessity not established, a visit limit reached, or an unmet deductible. Read the Explanation of Benefits — it states the reason.
Do I need a prescription?
For any route that involves a claim, yes in practice. Get it before the first session, naming the diagnosis and the reason hands-on treatment is indicated.
Does Circle Wellness take my insurance?
We bill NYSHIP directly. Other plans are self-pay, with itemised documentation provided for you to submit yourself.

Not sure which route applies to you?
We will point you at the right question to ask and who to ask it of, before you book anything. Please keep medical details off the web form — call and we will take it from there.